Sovereign Gold Bond vs Gold ETF: Returns, Tax, Costs & Key Differences
Gold has traditionally been an important part of Indian household wealth. It is purchased for jewellery, cultural occasions and as an investment. However, physical gold comes with practical concerns such as storage, making charges, purity verification and the risk of theft.
Investors who want exposure to gold without holding physical metal can consider financial products such as Sovereign Gold Bonds (SGBs) and Gold Exchange Traded Funds (Gold ETFs).
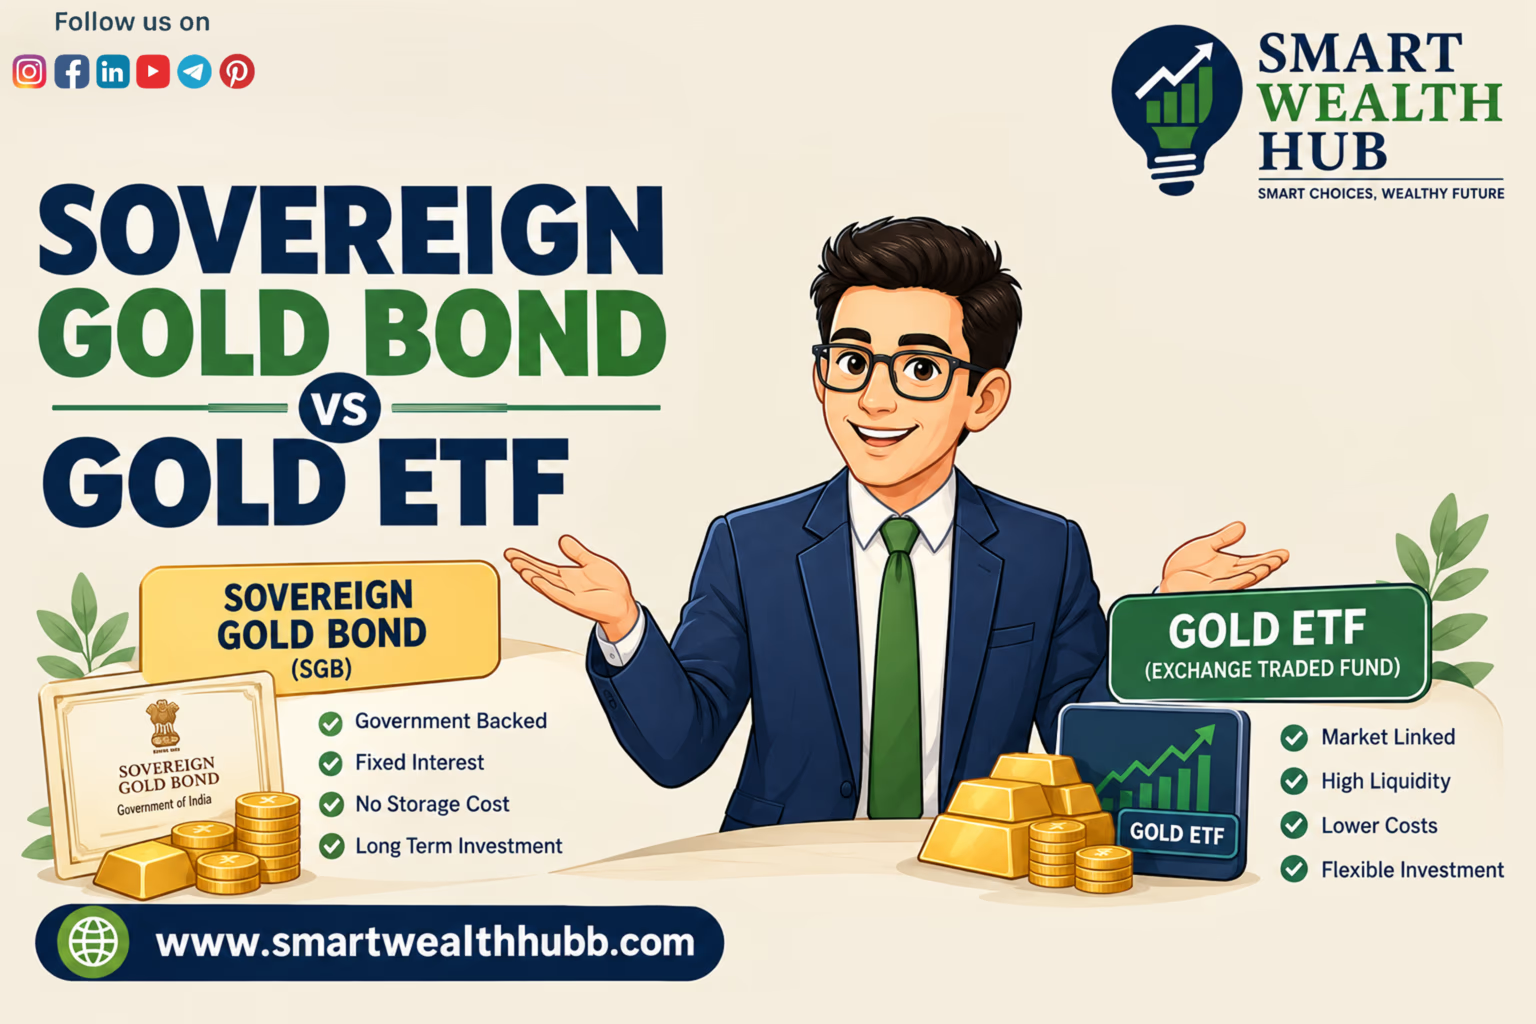
Although both are linked to gold, they are fundamentally different investment products. SGBs are government securities linked to the price of gold and carry a fixed interest component, while Gold ETFs are mutual-fund units designed to track domestic gold prices.
The important question is therefore not simply “Which is better?” but which product is more suitable for a particular investment objective, holding period, liquidity requirement and tax situation?
Key Takeaways
- SGBs and Gold ETFs both provide financial exposure to gold without requiring physical storage.
- SGBs carry a 2.50% annual interest rate on the nominal investment, paid semi-annually under the scheme terms.
- Gold ETFs do not pay a separate fixed interest; returns primarily arise from changes in the ETF's market value.
- Gold ETFs generally provide more convenient exchange-based buying and selling during market hours.
- SGBs have an 8-year maturity, with the scheme providing an early redemption facility from the fifth year on specified interest-payment dates; exchange trading is a separate exit route and depends on market liquidity.
- From Tax Year 2026-27, the SGB maturity capital-gains exemption has been clarified to apply where the investor subscribed at the original issue and continuously held the SGB until maturity.
- Listed Gold ETF units held for more than 12 months are generally subject to 12.5% long-term capital gains tax, without indexation; holdings of 12 months or less are generally taxed at applicable slab rates.
- Neither SGB investment nor Gold ETF investment should automatically be treated as an 80C tax deduction.
What Is a Sovereign Gold Bond?
A Sovereign Gold Bond (SGB) is a government security denominated in grams of gold. Instead of purchasing physical gold, the investor holds a security whose value is linked to the prevailing price of gold.
SGBs are issued by the Reserve Bank of India on behalf of the Government of India. The scheme provides a fixed interest rate of 2.50% per annum on the nominal value, payable semi-annually.
The value of the investment can therefore be affected by two components:
- Movement in the price of gold.
- Interest received at 2.50% per annum on the original nominal investment.
For example, suppose an investor originally subscribes to SGBs worth ₹1,00,000.
Annual interest:₹1,00,000 × 2.50% = ₹2,500
Over eight years, the nominal interest would total:₹2,500 × 8 = ₹20,000
This is a simple illustration and assumes the bond remains outstanding for the full eight-year period. The actual tax payable on the interest depends on the investor's applicable tax position.
The RBI's scheme documentation also provides for exchange tradability and collateral eligibility, subject to applicable rules and market conditions.
What Is a Gold ETF?
A Gold ETF is a mutual-fund investment product that seeks to track the domestic price of gold. Gold ETF units are traded on stock exchanges, allowing investors to buy or sell them through a demat and trading account.
Unlike an SGB, a Gold ETF does not provide a fixed 2.50% annual interest payment.
An investor's return generally comes from the change in the market value of the ETF units, after considering expenses and transaction-related costs.
For example:
If you invest ₹1,00,000 and the value of the Gold ETF rises by 30%, the investment becomes approximately:₹1,00,000 × 1.30 = ₹1,30,000
Gross gain:₹30,000
The actual post-tax return can be lower after applicable capital-gains tax, brokerage and other costs.
SGB vs Gold ETF: Key Differences
| Feature | Sovereign Gold Bond | Gold ETF |
|---|---|---|
| Underlying exposure | Gold price | Gold price |
| Issuer/structure | Government security issued through RBI | Mutual fund scheme |
| Interest | 2.50% p.a. on nominal value | No fixed interest |
| Maturity | 8 years | No fixed maturity |
| Exchange trading | Yes, subject to listing and liquidity | Yes |
| Early redemption under scheme | From 5th year on specified dates | Can generally sell on exchange during market hours |
| Minimum investment | Generally 1 gram | Generally 1 unit, depending on scheme |
| Expense ratio | No ETF-style expense ratio | Applicable scheme expenses/TER |
| Demat account | Can be held in demat | Required for exchange-traded units |
| Gold-price risk | Yes | Yes |
| Liquidity | Depends on exchange/market liquidity | Generally convenient through exchange |
| Fixed income component | 2.50% p.a. | None |
| Maturity exemption | Subject to applicable SGB tax provisions | Not applicable |
| Capital gains | Depends on type and route of transfer/redemption | Depends on holding period and tax law |
SGB vs Gold ETF: Liquidity and Exit
Liquidity is one of the most important differences.
Gold ETFs are traded on stock exchanges, so investors can generally buy or sell units during market hours. However, the actual execution price and liquidity depend on the particular ETF and prevailing market conditions.
SGBs have an eight-year maturity. The scheme also provides an early redemption facility from the fifth year on specified interest-payment dates. In addition, listed SGBs may be sold on an exchange before maturity, but the market price can differ from the theoretical value of the underlying gold and liquidity may vary.
Therefore, an investor who may need the money at short notice should examine the actual trading liquidity rather than assuming that every listed SGB can be sold immediately at its expected value.
Taxation: SGB vs Gold ETF in 2026
Tax treatment is one of the areas where older articles can be misleading.
SGB Taxation
The 2.50% SGB interest is taxable as income according to the applicable income-tax provisions.
For SGBs issued by the RBI, the 2026 Budget proposed an important clarification to the capital-gains exemption. From 1 April 2026, the exemption on redemption at maturity applies where the SGB was subscribed to by the investor at the original issue and held continuously until maturity.
This means investors should distinguish between:
- SGB subscribed to at the original issue and held continuously until maturity.
- SGB purchased later through an exchange or transferred before maturity.
- SGB sold before maturity.
The tax consequences can differ between these situations.
Gold ETF Taxation
For listed Gold ETF units, the current framework provides a 12-month threshold for long-term capital gains. Units held for more than 12 months are generally subject to 12.5% LTCG tax without indexation, while units held for 12 months or less are generally taxed at applicable slab rates.
Example of Gold ETF Tax
Suppose:
- Purchase value = ₹1,00,000
- Sale value = ₹1,40,000
- Capital gain = ₹40,000
- Holding period = more than 12 months
Illustrative LTCG tax: ₹40,000 × 12.5% = ₹5,000
A 4% health and education cess, along with any applicable surcharge, may increase the final tax liability.
This example is only an illustration. Actual tax depends on the investor's complete tax position.
Is There Any 80C Deduction for SGB or Gold ETF?
This is an important point for investors looking for tax-saving investments.
SGB investment and Gold ETF investment do not ordinarily qualify as deductions under Section 80C merely because the investment is made in gold.
Therefore, investing ₹1,00,000 in an SGB does not mean that ₹1,00,000 can automatically be deducted from taxable income under Section 80C.
The tax benefit associated with an SGB is instead primarily connected with its interest and applicable capital-gains treatment, subject to the relevant tax rules.
Also remember that the new tax regime is the default regime, while eligible taxpayers may opt for the old regime subject to applicable conditions.
Return Calculation: SGB vs Gold ETF
Consider a simplified example where gold appreciates by 40% over eight years.
Initial investment: ₹1,00,000
Assumed gold-linked appreciation: 40%
Value from gold-price appreciation: ₹1,40,000
SGB
The SGB also provides 2.50% annual interest on the original nominal value.
Approximate total interest over eight years: ₹1,00,000 × 2.50% × 8 = ₹20,000
Therefore, before considering taxation and other factors: ₹1,40,000 + ₹20,000 = ₹1,60,000
Gold ETF
Assuming the ETF broadly tracks the same gold-price movement: ₹1,00,000 → approximately ₹1,40,000
However, the ETF's actual return can differ from the gold price because of expense ratios, tracking difference and transaction costs.
This calculation is not a prediction of future gold prices. It simply demonstrates why the fixed SGB interest component can create a difference when an SGB is held under its applicable terms.
Which Is Suitable: SGB or Gold ETF?
There is no universal answer because the two products serve somewhat different purposes.
SGB may be considered when:
- You have a long investment horizon.
- You want exposure to gold along with a fixed interest component.
- You are comfortable with the maturity structure.
- You understand the tax conditions applicable to original subscription and maturity.
- You do not expect to require immediate liquidity.
Gold ETF may be considered when:
- You want exchange-based liquidity.
- You want the flexibility to buy and sell during market hours.
- You prefer an investment without a fixed maturity.
- You already have a demat and trading account.
- You want a product whose market value can be observed and traded throughout the trading session.
For a broader view of investment planning, investors can also explore related financial education resources and tools available through the investment and financial planning resources.
Are SGBs Still Available in 2026?
Investors should be careful with articles claiming that SGBs are always available for fresh subscription.
As of 2026, investors should verify the latest RBI or Government of India notification before assuming that a fresh SGB series is open for subscription.
Existing SGBs remain subject to their original scheme terms and maturity schedules. Listed SGBs may also be available through stock exchanges, depending on the particular series, seller availability and market liquidity.
This distinction is important because buying an existing SGB through an exchange is not necessarily the same as subscribing to a newly issued SGB.
Risks to Consider Before Investing in Gold
Gold is not a guaranteed-return investment.
Its market value can rise or fall depending on factors such as:
- International gold prices
- US dollar movements
- Interest rates
- Inflation expectations
- Geopolitical developments
- Central-bank buying
- Domestic currency movements
- Investor demand
For SGBs, investors also need to consider market-price risk if they sell before maturity.
For Gold ETFs, investors should consider expense ratios, tracking differences, brokerage and exchange liquidity.
Gold can therefore play a diversification role in a portfolio, but investors should consider their overall asset allocation rather than concentrating their portfolio in a single asset.
SGB vs Gold ETF: Final Comparison
| Investor Requirement | Relevant Consideration |
|---|---|
| Long-term gold exposure | SGB structure may be relevant |
| Fixed interest component | SGB |
| Exchange liquidity | Gold ETF |
| No fixed maturity | Gold ETF |
| Maturity-related tax exemption | SGB, subject to applicable conditions |
| Regular income | SGB provides 2.50% interest |
| Simple exchange-based trading | Gold ETF |
| Shorter investment horizon | Gold ETF may offer greater flexibility |
| Original SGB subscription and maturity holding | Special SGB tax treatment may apply |
The choice should ultimately be based on investment horizon, liquidity requirements, tax position, costs and portfolio allocation rather than simply comparing historical returns.
Conclusion
Sovereign Gold Bonds and Gold ETFs both provide investors with a way to gain exposure to gold without purchasing and storing physical metal. However, their structures are different.
SGBs combine gold-price exposure with a 2.50% annual interest component, while Gold ETFs primarily provide returns through changes in gold prices. Gold ETFs generally offer greater trading flexibility, whereas SGBs have a defined maturity structure and specific scheme-based redemption provisions.
Taxation is also an important consideration. The SGB maturity exemption has specific conditions under the rules applicable from 2026, while listed Gold ETFs have their own capital-gains treatment based on the holding period.
Before investing, compare the after-tax return, liquidity, costs, holding period and role of gold in your overall portfolio. Investors should also verify the latest tax and regulatory provisions because gold-investment rules can change through Finance Acts, notifications and regulatory updates.
Frequently Asked Questions
Which is better, SGB or Gold ETF?
Neither is universally better. SGBs provide a 2.50% annual interest component and have a defined maturity structure, while Gold ETFs generally provide greater exchange-based liquidity and flexibility. The suitable option depends on the investor's objective, holding period and liquidity requirements.
Is SGB interest tax-free?
No. The 2.50% interest paid on SGBs is taxable according to the applicable income-tax provisions.
What is the tax rate on Gold ETFs in 2026?
For listed Gold ETF units, holdings of more than 12 months are generally treated as long-term and taxed at 12.5% without indexation. Holdings of 12 months or less are generally taxed at applicable slab rates.
Is there an 80C deduction for investing in SGB or Gold ETF?
No. Simply investing in an SGB or Gold ETF does not ordinarily create an 80C deduction. Investors should distinguish between investment products that qualify for specific deductions and investments that merely receive capital-gains or income-tax treatment.
Are fresh Sovereign Gold Bonds available in 2026?
Investors should check the latest RBI and Government of India notifications before assuming that a new SGB series is available. Existing SGBs continue according to their respective terms, and some may trade on recognised stock exchanges subject to market liquidity.
These articles are for awareness. For advice suited to your goals, talk to our team.
Book a free consultationDisclaimer: Views in this article are for educational purposes and do not constitute personalised financial, tax, or investment advice. Markets involve risk — read all related documents carefully.
Comments0
No comments yet. Be the first to share a thought.