Home & Property Insurance: Benefits, Coverage, Protection and Claims Guide
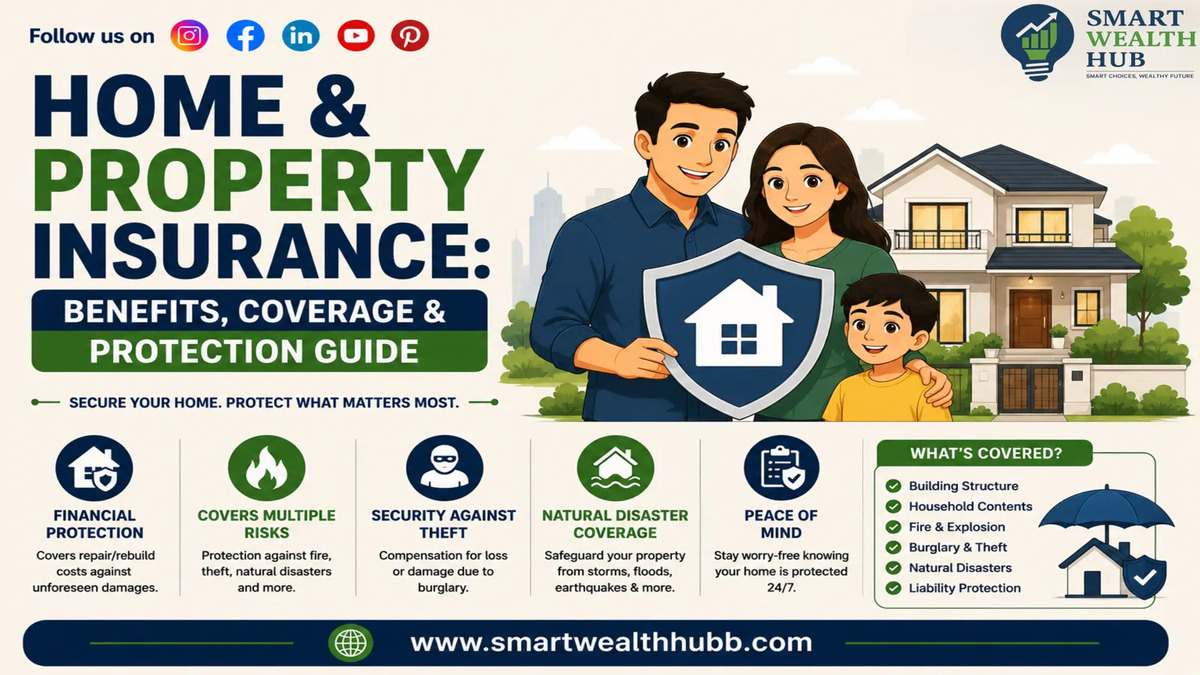
Your home is often one of the largest financial assets you will ever own. Whether it is a self-occupied house, an apartment, a rented property or an investment property, unexpected events can cause substantial financial damage.
Fire, flooding, storms, earthquakes, burglary and accidental damage can result in repair or replacement expenses running into lakhs of rupees. Home and property insurance helps reduce this financial burden by providing coverage for specified risks and losses.
However, buying a policy without understanding what is covered can create problems during a claim. The right sum insured, policy type, exclusions and optional covers are just as important as the premium.
This guide explains how home and property insurance works in India, what it generally covers, how to calculate the required coverage and what tax and regulatory considerations property owners should understand.
Related financial planning tool: Before choosing protection for your property, you can review your broader financial requirements using a financial planning calculator.
What Is Home & Property Insurance?
Home and property insurance is a general insurance product designed to provide financial protection against loss or damage to insured property due to covered events.
Depending on the policy, coverage may include:
- The physical structure of the home
- Furniture and household contents
- Electrical and electronic appliances
- Jewellery and valuables under specified conditions
- Loss caused by fire
- Natural disasters
- Burglary or theft
- Accidental damage
- Third-party liability
The exact scope depends on the policy wording and optional covers selected.
Property insurance generally follows the principle of insurable interest. This means the person buying insurance should have a financial interest in the property and would suffer financially if it were damaged or destroyed. IRDAI's consumer guidance identifies property insurance as covering assets against specified risks and explains that the insured must have an insurable interest in the property.
Why Is Home Insurance Important?
Many people insure their car or purchase health insurance but leave their most valuable physical asset uninsured.
A major property loss can affect years of savings.
For example, assume the rebuilding cost of a residential property is ₹60 lakh.
If a major fire causes structural damage requiring repairs costing ₹30 lakh, paying entirely from personal savings could significantly affect other financial goals such as:
- Retirement planning
- Children's education
- Emergency funds
- Investments
- Loan repayments
If the property is adequately insured and the loss falls within policy coverage, insurance can reduce the financial impact.
Home insurance is therefore primarily a risk-management tool, not an investment product.
Types of Home & Property Insurance Coverage
1. Building Structure Insurance
This covers the physical structure of the property, subject to policy terms.
It may include:
- Walls
- Roof
- Floors
- Permanent fixtures
- Built-in fittings
- Attached structures
The coverage amount should generally reflect the cost of rebuilding the property, rather than its market value.
Land value is normally not the same as reconstruction cost because land generally cannot be destroyed by fire or similar events.
Example Calculation
Suppose:
- Built-up area: 2,000 square feet
- Estimated reconstruction cost: ₹2,500 per square foot
Estimated rebuilding cost:
2,000 × ₹2,500 = ₹50,00,000
In this simplified example, the building sum insured could be approximately ₹50 lakh, subject to professional valuation and policy requirements.
2. Home Contents Insurance
Contents insurance protects movable items inside the property.
Depending on policy terms, this may include:
- Furniture
- Television
- Refrigerator
- Washing machine
- Computers
- Air conditioners
- Household appliances
A homeowner should create a realistic inventory of household possessions.
Example
Household Item Estimated Value Furniture ₹6,00,000 Electronics ₹3,00,000 Appliances ₹2,00,000 Other household items ₹2,00,000 Total ₹13,00,000 In this example, a contents cover of approximately ₹13 lakh may be considered, depending on policy terms and valuation requirements.
Keeping invoices, photographs and purchase records can also help support future claims.
3. Fire and Allied Perils Coverage
Fire-related coverage is one of the major components of property insurance.
Depending on the policy, covered perils may include events such as:
- Fire
- Lightning
- Explosion or implosion
- Aircraft damage
- Storm
- Cyclone
- Flood
- Inundation
- Impact damage
- Bursting or overflowing water tanks and pipes
- Other specified events
IRDAI's guidance on standard fire and property policies explains the importance of checking the specified insured perils and policy conditions.
Coverage should always be confirmed from the individual policy wording because not every risk is automatically included.
4. Burglary and Theft Protection
Loss caused by burglary or housebreaking may require separate coverage or an additional section within a comprehensive home insurance policy.
Coverage conditions may depend on:
- Forced entry requirements
- Proof of burglary
- Police reporting requirements
- Security arrangements
- Item valuation
Simple disappearance of an item may not automatically qualify as an insured burglary claim.
5. Natural Disaster Protection
Natural disasters can create significant property damage.
Depending on the policy and selected coverage, protection may include risks such as:
- Flood
- Cyclone
- Storm
- Earthquake
- Landslide
- Other specified natural events
Property owners should carefully review geographical risks before purchasing insurance.
For example, a property located in a flood-prone area may require particular attention to flood coverage, exclusions and deductibles.
How Much Home Insurance Coverage Do You Need?
One of the most common mistakes is selecting the sum insured based only on the property purchase price.
The purchase price may include:
Property Value = Land Value + Building Value + Location Premium
However, the building insurance requirement is generally more closely related to reconstruction or replacement cost.
A Simple Coverage Formula
Building Sum Insured = Built-up Area × Estimated Reconstruction Cost per Square Foot
For example:
- Area: 1,500 sq. ft.
- Reconstruction cost: ₹3,000 per sq. ft.
1,500 × ₹3,000 = ₹45,00,000
Estimated building cover: ₹45 lakh
Add contents separately:
- Building: ₹45 lakh
- Household contents: ₹10 lakh
Potential total property protection requirement:
₹55 lakh
This is only an illustrative calculation. Construction costs, location, property design and policy conditions can materially affect the appropriate sum insured.
You may also explore more financial education resources in the latest insurance and financial planning blogs
What Is Usually Not Covered?
Every insurance policy contains exclusions and limitations.
Common exclusions may include:
- Normal wear and tear
- Gradual deterioration
- Poor maintenance
- Intentional damage
- Certain structural defects
- War-related events
- Nuclear risks
- Losses outside specified policy coverage
- Uninsured property or valuables
Some policies may also apply:
- Deductibles
- Excess amounts
- Sub-limits
- Depreciation
- Specific exclusions for high-value items
Never assume that a risk is covered simply because the policy is described as "comprehensive."
Always review the policy wording.
Understanding Underinsurance
Underinsurance occurs when the property is insured for less than its actual required value.
Consider this example:
- Actual rebuilding value: ₹1 crore
- Insurance sum insured: ₹50 lakh
- Loss: ₹40 lakh
The claim settlement may be affected by policy conditions relating to adequate insurance and average clauses.
For this reason, selecting a low sum insured simply to reduce the premium can create a substantial financial risk.
Property values and reconstruction costs should also be reviewed periodically.
Tax Benefits on Home & Property Insurance in India
A common misconception is that all insurance premiums automatically qualify for tax deductions.
This is not correct.
Premiums for ordinary home or property insurance generally do not automatically receive a dedicated income-tax deduction simply because the property is insured.
Tax benefits should not be confused with:
- Life insurance deductions under eligible provisions
- Health insurance deductions under Section 80D
- Home-loan principal deductions under Section 80C
- Eligible housing-loan interest deductions under Section 24(b)
For AY 2026–27, the Income Tax Department lists Section 80C as having a combined maximum deduction of ₹1.5 lakh for eligible investments and payments, while Section 80D relates specifically to qualifying health insurance and medical expenditure—not ordinary home insurance premiums.
Example
Suppose an individual pays:
- Home insurance premium: ₹12,000
- Life insurance premium: ₹60,000
- Health insurance premium: ₹25,000
The ₹12,000 home insurance premium should not automatically be assumed to qualify under Sections 80C or 80D.
Tax treatment can vary depending on the taxpayer, use of the property and applicable tax provisions. Professional tax advice may be appropriate in complex situations.
Regulatory Context for Property Insurance
Insurance in India operates within the regulatory framework overseen by the Insurance Regulatory and Development Authority of India (IRDAI).
Property insurance policies may be issued in standardised or insurer-specific formats, depending on the product category.
IRDAI guidance identifies the Standard Fire and Allied Perils policy as an important property insurance product and also notes the availability of specialised policies for burglary, valuables and package protection for homes and other properties.
Policyholders should:
- Read the policy schedule.
- Verify the insured property details.
- Check the sum insured.
- Review covered perils.
- Understand exclusions.
- Check deductibles and excesses.
- Understand claim notification requirements.
How to File a Home Insurance Claim
The exact procedure depends on the insurer, but a typical claim process may involve the following steps.
Step 1: Inform the Insurer
Notify the insurer as soon as reasonably possible after the incident.
Step 2: Take Reasonable Steps to Prevent Further Loss
If it is safe to do so, take reasonable steps to prevent additional damage.
Step 3: Collect Evidence
Useful documentation may include:
- Photographs
- Videos
- Purchase invoices
- Repair estimates
- Property records
Step 4: File a Police Complaint Where Required
Theft or burglary claims may require an FIR or other police documentation.
Step 5: Survey and Assessment
The insurer may appoint a surveyor to assess the loss.
Step 6: Claim Settlement
After documentation and assessment, the claim may be settled according to the policy terms, approved loss amount and applicable deductions.
Do not dispose of damaged items before receiving appropriate guidance if they may be required for inspection.
How to Choose the Right Home Insurance Policy
Before purchasing, compare the following:
1. Coverage Scope
Understand exactly which risks are included.
2. Sum Insured
Ensure that the building and contents are adequately insured.
3. Natural Disaster Coverage
Review risks relevant to the property's geographical location.
4. Contents Protection
Check whether household items are adequately covered.
5. Valuables
High-value jewellery, artwork and collectibles may require specific declarations or additional coverage.
6. Deductibles
A lower premium may involve a higher deductible.
7. Exclusions
Read exclusions before purchasing rather than discovering them during a claim.
Final Thoughts
Home and property insurance can play an important role in protecting one of your largest financial assets. A suitable policy can help manage the financial consequences of fire, natural disasters, burglary and other covered risks.
The most important factors are not just the premium but also:
- Adequate sum insured
- Correct valuation
- Relevant risk coverage
- Contents protection
- Understanding exclusions
- Proper documentation
Reviewing your coverage periodically is particularly important when reconstruction costs increase, renovations are completed or expensive household assets are purchased.
Insurance should be treated as part of a broader financial protection strategy alongside emergency savings, health protection, life insurance and long-term investment planning.
For more guides on insurance, investments, taxation and personal finance, visit the financial education blog section.
Frequently Asked Questions
What does home insurance cover?
Home insurance may cover the building structure, household contents and specified losses caused by events such as fire, natural disasters, burglary and accidental damage, depending on the policy.
How much home insurance should I buy?
The building cover should generally be based on an appropriate reconstruction or replacement value, while contents should be insured based on their estimated replacement value.
Does home insurance cover land value?
Generally, property insurance focuses on insurable physical assets such as the building and contents. Land value is not the same as reconstruction cost.
Is home insurance mandatory in India?
Home insurance is generally not universally mandatory for all homeowners, although lenders may impose insurance-related requirements for mortgaged properties.
Is home insurance premium eligible for tax deduction?
An ordinary home insurance premium does not automatically qualify for a specific personal income-tax deduction merely because it is paid for property insurance. Tax treatment can depend on applicable provisions and the circumstances of the taxpayer.
These articles are for awareness. For advice suited to your goals, talk to our team.
Book a free consultationDisclaimer: Views in this article are for educational purposes and do not constitute personalised financial, tax, or investment advice. Markets involve risk — read all related documents carefully.
Comments0
No comments yet. Be the first to share a thought.