Miscellaneous Insurance Policies in India: Types, Benefits and Coverage Guide
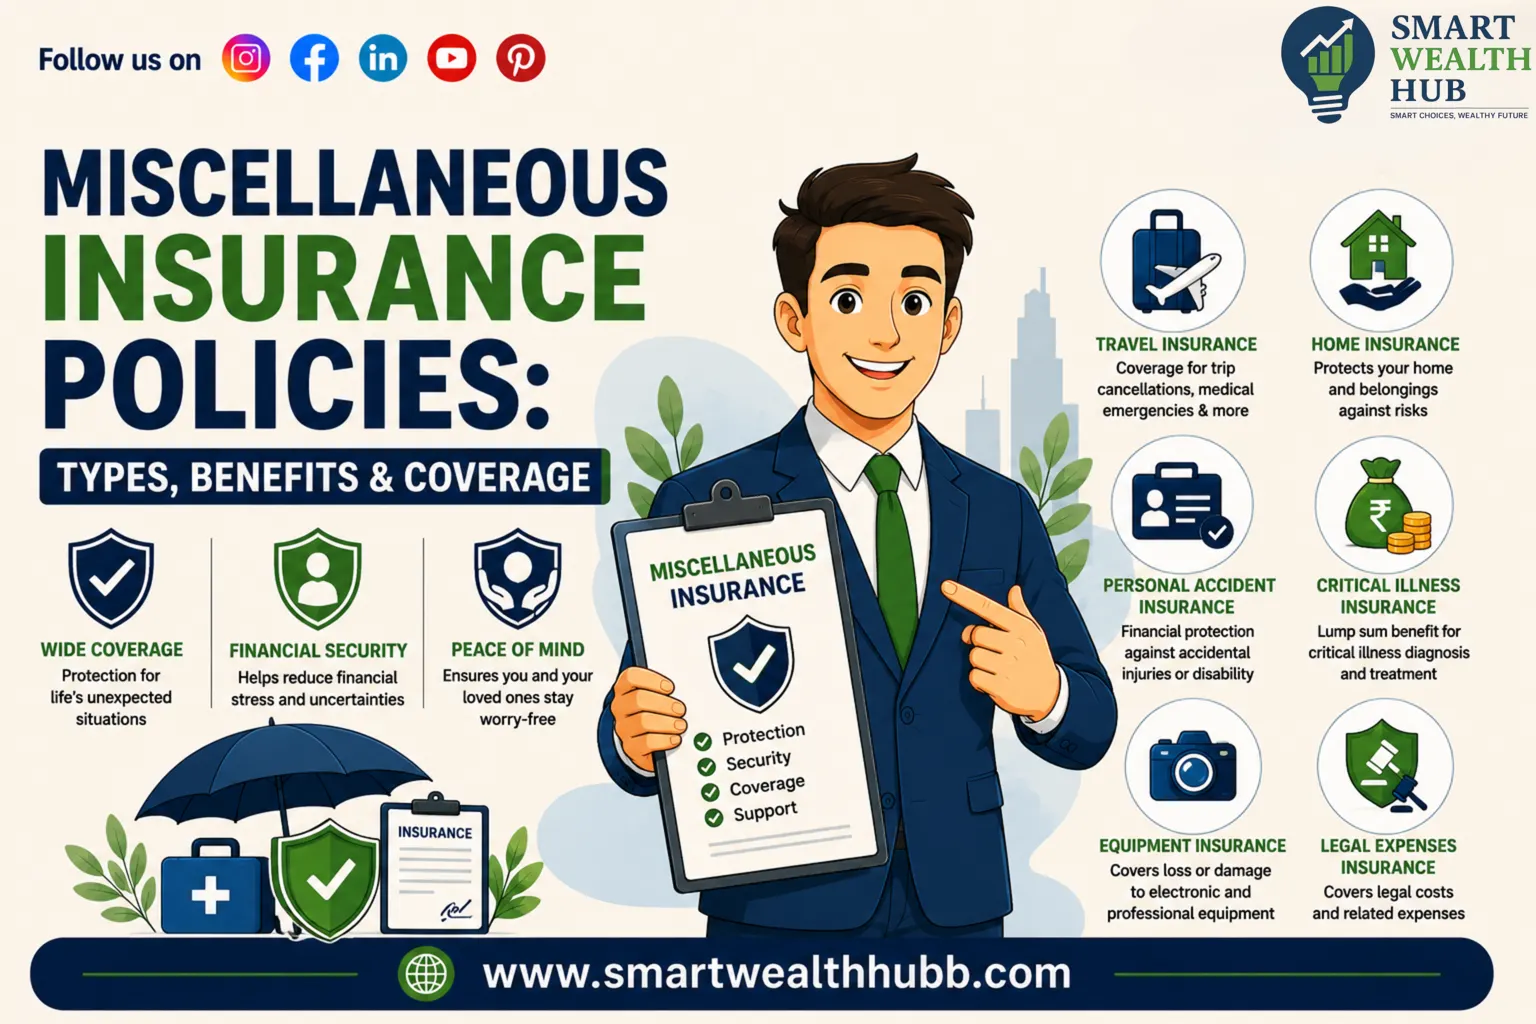
Insurance is not limited to life, health and motor policies. Individuals, professionals and businesses face many other financial risks, including property damage, theft, cybercrime, legal liability, equipment breakdown and accidents.
These risks can often be addressed through miscellaneous insurance policies, a broad category of general insurance products designed to protect against specific and diverse exposures.
Under the Indian insurance framework, general insurance includes fire, marine and miscellaneous insurance. The miscellaneous category covers a wide range of policies, including personal accident, liability, burglary, cyber, engineering, electronic equipment and other specialised covers.
This guide explains the major types of miscellaneous insurance policies, their benefits, coverage, exclusions, premium factors and regulatory considerations in India.
What Is Miscellaneous Insurance?
Miscellaneous insurance refers to general insurance policies that protect against risks that may not fall primarily under life, standard health, fire or marine insurance.
The category can include protection for:
- Personal accidents
- Property and valuables
- Theft and burglary
- Legal liability
- Cyber incidents
- Professional risks
- Equipment and machinery
- Employee-related liabilities
- Money and cash in transit
- Travel-related risks
- Engineering and construction risks
Insurance products in this category can be highly specialised. The exact coverage depends on the policy wording, selected sum insured, endorsements, exclusions and applicable conditions.
The Insurance Regulatory and Development Authority of India (IRDAI) maintains a wide range of approved non-life insurance products, including cyber insurance, burglary insurance, fidelity guarantee, money insurance, machinery breakdown and liability policies.
Why Is Miscellaneous Insurance Important?
Unexpected events can create financial losses that are much larger than the cost of an insurance premium.
For example, consider a small business with:
- Equipment value: ₹15 lakh
- Stock value: ₹20 lakh
- Annual revenue: ₹1 crore
A major burglary or equipment breakdown could affect both assets and business operations.
If an uninsured event causes a ₹10 lakh loss, the business may need to arrange funds immediately from:
- Business reserves
- Personal savings
- Loans
- Credit facilities
Appropriate insurance can transfer part of the financial risk to the insurer, subject to the policy's terms and limits.
Miscellaneous insurance is therefore particularly useful where the financial impact of a specific event could be difficult to absorb independently.
Types of Miscellaneous Insurance Policies
1. Personal Accident Insurance
Personal accident insurance provides financial protection against accidental bodily injury, disability or death, depending on the policy terms.
Coverage may include:
- Accidental death
- Permanent total disability
- Permanent partial disability
- Temporary total disability
- Certain medical expenses, where included
Example Calculation
Suppose a person purchases a personal accident policy with a sum insured of ₹25 lakh.
If the policy provides 100% benefit for accidental death, the maximum benefit may be ₹25 lakh, subject to policy terms and claim conditions.
For partial disabilities, insurers may apply a percentage specified in the policy schedule.
For example:
Sum Insured × Disability Percentage = Policy Benefit
₹25,00,000 × 40% = ₹10,00,000
The actual claim depends entirely on the policy wording and applicable benefit table.
2. Burglary and Theft Insurance
Burglary insurance protects businesses or property owners against specified losses resulting from burglary or theft.
It may cover:
- Stock
- Furniture
- Fixtures
- Equipment
- Other insured contents
IRDAI notes that burglary policies may cover burglary and, depending on the policy terms, theft. Conditions relating to occupancy and security may also apply.
Important Consideration
A fire policy does not automatically mean burglary is covered.
Insurance works on the basis of insured perils. A loss caused by an event not covered under the policy may not be payable.
3. Property and All-Risk Insurance
Property-related miscellaneous policies can protect valuable assets against accidental loss or damage.
Depending on the policy, coverage may be available for:
- Jewellery
- Valuable personal belongings
- Electronic devices
- Portable equipment
- Other specifically insured assets
IRDAI notes that certain valuables may require specific coverage and proper valuation rather than relying solely on a general property policy.
Why Correct Valuation Matters
Suppose jewellery worth ₹10 lakh is insured for only ₹5 lakh.
In the event of a total covered loss, the claim may be restricted by the sum insured and applicable policy conditions.
On the other hand, significantly over-insuring property may result in unnecessarily high premiums without increasing compensation beyond the actual insurable value.
4. Cyber Insurance
Cyber insurance is becoming increasingly relevant for individuals and businesses.
Depending on the product, coverage may include financial losses arising from:
- Unauthorised online transactions
- Identity theft
- Phishing incidents
- Data breaches
- Cyber extortion
- Malware or ransomware incidents
- Legal or notification costs for businesses
IRDAI's non-life product listings include retail cyber insurance products among the miscellaneous insurance offerings available in India.
Example
A business suffering a cyber incident may incur:
| Expense | Estimated Cost |
|---|---|
| IT investigation | ₹1,50,000 |
| System restoration | ₹2,00,000 |
| Legal expenses | ₹1,00,000 |
| Customer communication | ₹50,000 |
| Total | ₹5,00,000 |
Whether these costs are payable depends on the specific cyber policy and selected coverage.
5. Public Liability Insurance
Public liability insurance protects businesses against legal liability arising from accidental injury or property damage to third parties.
For example, a customer may suffer an injury at a business premises.
The business could face costs relating to:
- Legal defence
- Compensation
- Court-awarded damages
- Certain associated expenses
The extent of coverage depends on the liability limit and policy wording.
Businesses dealing with customers, visitors, vendors or the general public should carefully evaluate their potential third-party exposure.
6. Professional Indemnity Insurance
Professional indemnity insurance is designed primarily for professionals who may face legal claims arising from professional errors, omissions or negligence.
It may be relevant for:
- Consultants
- Chartered accountants
- Architects
- Doctors
- Engineers
- IT professionals
- Other service providers
For example, if professional advice results in a client claiming financial loss, the professional may face legal defence costs.
Professional indemnity insurance may help cover specified legal liabilities, subject to the policy.
7. Fidelity Guarantee Insurance
Fidelity guarantee insurance protects businesses against certain financial losses caused by dishonest or fraudulent acts of employees.
Potential losses may arise from:
- Employee fraud
- Misappropriation
- Theft of funds
- Dishonest financial transactions
IRDAI's non-life insurance product database includes fidelity guarantee policies among available miscellaneous insurance products.
This cover can be particularly relevant for organisations where employees handle:
- Cash
- Financial transactions
- Customer funds
- Valuable inventory
8. Money Insurance
Money insurance can protect against specified losses involving cash.
Coverage may include, depending on the policy:
- Cash kept at business premises
- Cash in transit
- Cash handled by authorised employees
For example, a retail business regularly transferring ₹5 lakh in cash may face risks during transportation.
The policy should clearly specify:
- Maximum cash limit
- Transit conditions
- Security requirements
- Locations covered
9. Electronic Equipment Insurance
Modern businesses depend heavily on electronic equipment.
Electronic equipment insurance may cover specified accidental physical loss or damage to:
- Computers
- Servers
- Networking equipment
- Office electronics
- Other insured systems
IRDAI's product listings include electronic equipment insurance products.
Businesses should also check whether the policy covers only physical damage or includes additional protection for data restoration and business interruption.
10. Machinery Breakdown Insurance
Machinery breakdown insurance can protect businesses against sudden and unforeseen mechanical or electrical breakdown of insured machinery.
This may be relevant for:
- Manufacturing units
- Workshops
- Processing facilities
- Industrial businesses
Example
Suppose a machine is valued at ₹30 lakh.
A covered breakdown causes repair costs of ₹4 lakh.
If the policy:
- Covers the breakdown
- Has adequate sum insured
- Includes no relevant exclusion
- Has an applicable deductible of ₹25,000
A simplified illustration would be:
Covered Repair Cost − Deductible = Potential Claim
₹4,00,000 − ₹25,000 = ₹3,75,000
This is only an illustrative calculation. Actual claims depend on policy wording, depreciation and other applicable conditions.
Benefits of Miscellaneous Insurance
Miscellaneous insurance can provide several important benefits.
Financial Risk Protection
Insurance can reduce the financial impact of sudden and unexpected losses.
Business Continuity
Some policies help businesses manage losses involving equipment, property or legal liability.
Customised Coverage
Policies can often be selected according to the specific risks faced by an individual or business.
Liability Protection
Liability insurance can provide protection against potentially significant third-party claims.
Asset Protection
Valuable personal and business assets can be insured against specified risks.
What Does Miscellaneous Insurance Usually Exclude?
Exclusions vary significantly between policies.
Common exclusions may include:
- Deliberate or fraudulent acts
- Normal wear and tear
- Gradual deterioration
- Certain pre-existing damage
- War-related risks
- Nuclear risks
- Contractual liabilities not covered by the policy
- Losses outside geographical limits
- Failure to comply with security requirements
Always read:
- Policy schedule
- Product brochure
- Terms and conditions
- Exclusions
- Deductible clauses
- Endorsements
Never assume that two policies with similar names provide identical coverage.
How Is the Sum Insured Decided?
The appropriate sum insured depends on the type of policy.
For Property
The value may be based on:
- Market value
- Reinstatement value
- Replacement cost
For Liability
The business should evaluate potential maximum legal exposure.
For Personal Accident
The sum insured should consider:
- Income
- Financial dependents
- Existing insurance
- Financial obligations
A simple risk assessment formula can help:
Potential Financial Loss × Probability of Significant Exposure = Risk Priority
The calculation does not replace professional underwriting, but it can help identify areas requiring stronger protection.
You can also review other financial planning resources and tools through calculators and tools to understand how insurance requirements fit into an overall financial plan.
Tax Benefits and Tax Treatment
Tax treatment depends on the type of insurance and the applicable provisions of the Income-tax Act.
Health Insurance
Eligible health insurance premiums may qualify for deductions under Section 80D under the applicable tax regime and conditions.
For example, the Income Tax Department currently lists deductions of up to ₹25,000 for eligible premiums for self, spouse and dependent children, increasing to ₹50,000 where the relevant covered person is a senior citizen. Similar limits apply separately for eligible parents, subject to conditions. Preventive health check-ups up to ₹5,000 are included within the applicable overall limit.
Life Insurance
Eligible life insurance premiums may qualify under Section 80C, subject to conditions and the combined deduction limit of ₹1.5 lakh with other eligible investments and expenses.
Other Miscellaneous Insurance
Personal accident, property, cyber, liability and other miscellaneous insurance premiums do not automatically qualify for personal tax deductions merely because they are insurance policies.
Business-related insurance premiums may have different tax treatment depending on their nature and whether they are incurred wholly and exclusively for business or professional purposes. Tax treatment should be verified with a qualified tax professional.
How to Choose the Right Miscellaneous Insurance Policy
Before purchasing a policy, consider the following:
1. Identify Your Risks
List the assets, liabilities and events that could cause a significant financial loss.
2. Calculate Your Potential Exposure
Estimate the maximum financial loss from a major incident.
3. Select an Appropriate Sum Insured
Avoid both underinsurance and unnecessary overinsurance.
4. Compare Coverage, Not Just Premium
A lower premium may come with:
- Lower coverage
- Higher deductibles
- More exclusions
- Lower liability limits
5. Check Claim Conditions
Understand the documents and procedures required for making a claim.
6. Read Exclusions Carefully
The most important part of an insurance policy is often understanding what is not covered.
For more educational articles on insurance, investments and financial planning, explore related guides and blogs.
Conclusion
Miscellaneous insurance policies provide protection against a broad range of risks that may otherwise remain uninsured. From cybercrime and burglary to liability claims and machinery breakdown, specialised insurance can help individuals and businesses manage potentially significant financial losses.
The right policy depends on the nature of the risk, value of assets, potential liability and ability to absorb a financial loss.
Before purchasing any policy, compare coverage, exclusions, deductibles, policy limits and claim conditions. Insurance should be selected based on actual risk exposure rather than simply choosing the lowest premium.
Frequently Asked Questions
What is miscellaneous insurance?
Miscellaneous insurance is a broad category of general insurance covering specialised risks such as personal accidents, burglary, cyber incidents, liability, machinery breakdown and other specific exposures.
Is miscellaneous insurance the same as general insurance?
Miscellaneous insurance is generally considered a category within the broader general insurance sector. General insurance in India includes fire, marine and miscellaneous insurance.
Who should buy miscellaneous insurance?
Individuals and businesses facing risks involving valuable assets, accidents, cybercrime, legal liability, theft or equipment can consider appropriate miscellaneous insurance policies.
Does miscellaneous insurance cover every type of loss?
No. Every policy has defined coverage, limits, conditions and exclusions. A claim is generally payable only when the loss falls within the insured coverage and policy terms.
Are miscellaneous insurance premiums eligible for tax deductions?
Not all miscellaneous insurance premiums qualify for personal tax deductions. Tax treatment depends on the policy type, purpose and applicable provisions of the Income-tax Act.
These articles are for awareness. For advice suited to your goals, talk to our team.
Book a free consultationDisclaimer: Views in this article are for educational purposes and do not constitute personalised financial, tax, or investment advice. Markets involve risk — read all related documents carefully.
Comments0
No comments yet. Be the first to share a thought.